Market Notes
The AI Buildout's Cracks Are in the Debt, October 2026

The AI buildout isn't stalling because the technology stopped working. It's stalling where the money has to show up on a schedule. Oracle sent a force majeure notice on a 2.45 gigawatt data center campus in New Mexico, and the thing standing in the way is a 0.6 mile piece of natural gas pipeline that a state land commissioner won't permit. I think the credit side of this trade decides the next 6 months, not the chip side.
What the Data Shows
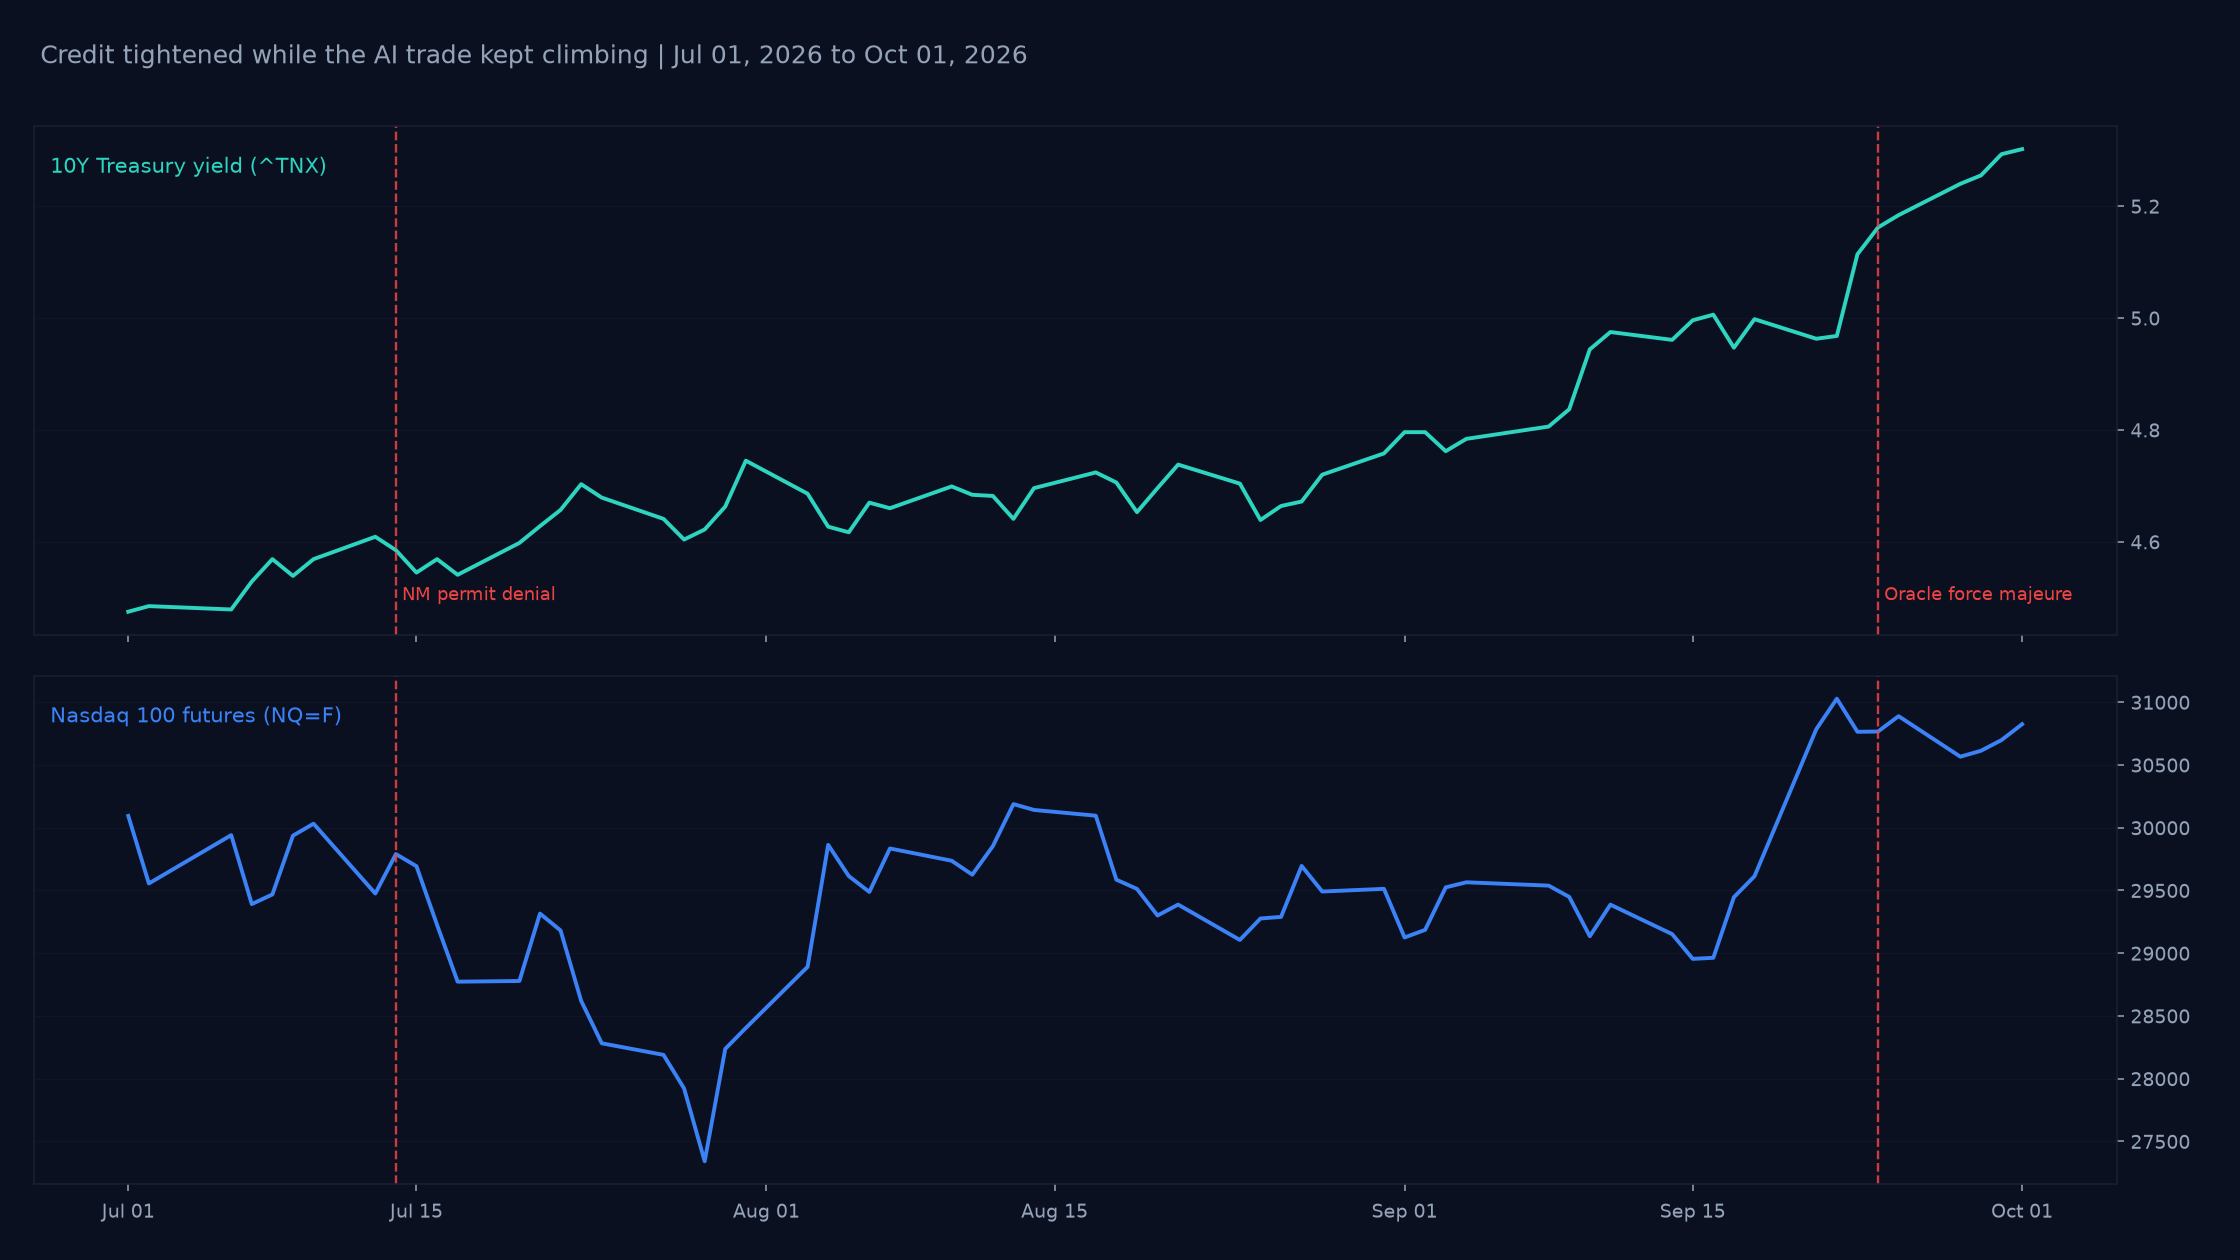
Start with the permit, because it's the cleanest fact here. The New Mexico State Land Office denied Energy Transfer's request for reconsideration on July 14, 2026, after an initial denial in March 2026, covering two rights of way and one business lease for a 0.6 mile stretch of a 17 mile natural gas pipeline. Commissioner Stephanie Garcia Richard's stated reason was that the applications were not in the best interest of the state land trust. That short stretch of pipe carries the gas for the $BE fuel cell microgrid that powers the campus, so one local permit decision gates 2,462 megawatts. $ORCL dated its force majeure notice September 24, 2026, and Bloomberg reported it the next day.
Oracle's own filing shows why deferring a 2028 bill is worth the headline risk. In the quarter ended August 31, 2026 the company spent $28.5 billion on capital expenditures and brought in $23.1 billion from operations, per the 10-Q it filed September 11, 2026. That same filing carries $125.3 billion of notes payable and other borrowings plus $30.6 billion of operating lease liabilities against $36.4 billion of cash. Outspending operating cash flow by $5.4 billion in 90 days is a choice, and the lenders on this project read that filing as well as I do.
Credit repriced in the same stretch. The ICE BofA US High Yield index effective yield went from 7.46% on September 21, 2026 to 8.08% on September 29, and the CCC and lower slice sits at 16.48%, both per FRED. The 10 year closed at 5.28% on October 1, 2026 after touching 5.29% the day before. Nasdaq 100 futures were up 0.94% over the 5 sessions to October 1, so stocks aren't pricing what credit is pricing.
Why It Matters for Your Portfolio
The AI trade has quietly become a credit trade, and the IPO pipeline is where that shows up next. Nscale's S-1, filed September 18, 2026, lists $103.4 billion of active and contracted total contract value as of August 31, 2026, including up to roughly $44.6 billion from Anthropic alone. Against that sits a $1.02 billion net loss for the 6 months ended June 30, 2026 and a risk factor saying the company will require additional capital. Contracts that size are only as good as the financing behind them, and financing gets priced off the same curve that just moved 10 basis points in a week.
What I'm Watching
2 dates on the New Mexico campus. The microgrid air permit deadline is November 23, 2026, and the revised pipeline in service target is February 2027, pushed back from August 2026. If either one slips again, the 2028 energization date goes with it, and the roughly $18 billion of bank debt behind the campus gets repriced rather than just discussed; the Financial Times already had that paper at 89 to 91 cents on the dollar in late September.
On the market side I want to see whether the high yield index holds under 8.50% and whether the 10 year stays above 5.25%. I could be wrong on the timing, because permit fights get settled quietly all the time. What I don't think is noise is that financing, not compute, is now the binding constraint.
Related Reading: The AI Bubble's Early Tripwires Are Already Flashing and AI Data Center Debt Is Sitting in Insurance Money, 2026
Disclosure: as of September 2, 2026 I hold positions in $ORCL and $BE, both named above.
Howard is a full-time trader based in New Jersey with 13 years of experience across Forex, crypto, equities, and futures. He started Position Note to document his trades and analysis in public. All positions are disclosed. Nothing here is personalized investment advice.